RSI Pair Trading Strategy in Python for IBKR: Multi-Timeframe Signals and Basket Logic
How a multi-timeframe RSI pair-trader can be translated into a Python IBKR application with current RSI triggers, pullback confirmation, recovery logic and basket P&L control.
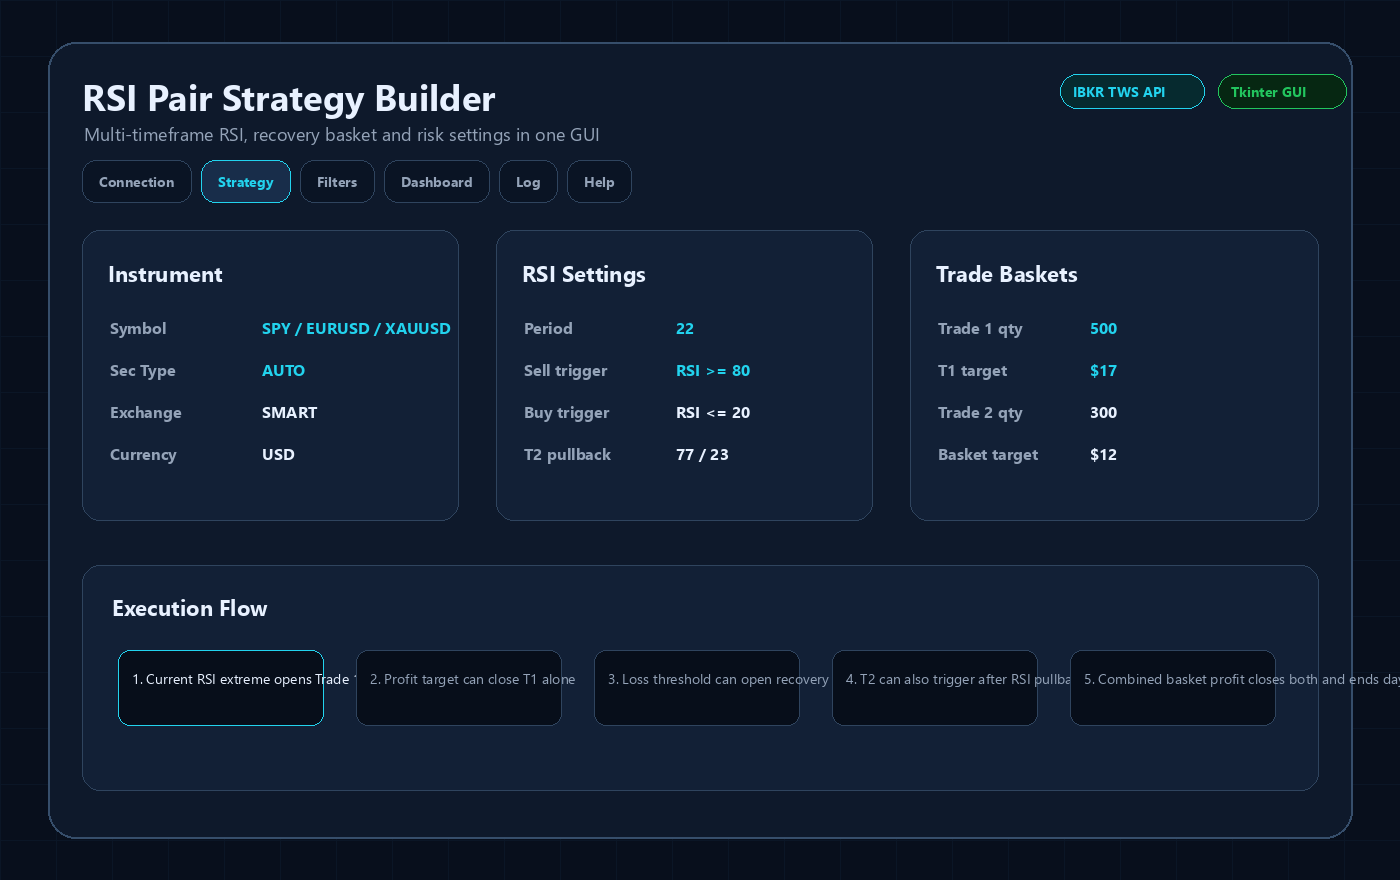
What This Page Covers
The goal of this RSI pair-trader design is to make the strategy rules objective enough for software: which timeframe triggers, when Trade 1 opens, when Trade 2 opens, what counts as recovery and when the basket is finished.
Technical Breakdown
Signal model
The app watches RSI values across enabled timeframes from M5 to D1. Current-candle RSI can trigger an initial overbought or oversold entry, while previous-closed and current RSI values can be used for the second pullback entry.
Basket state
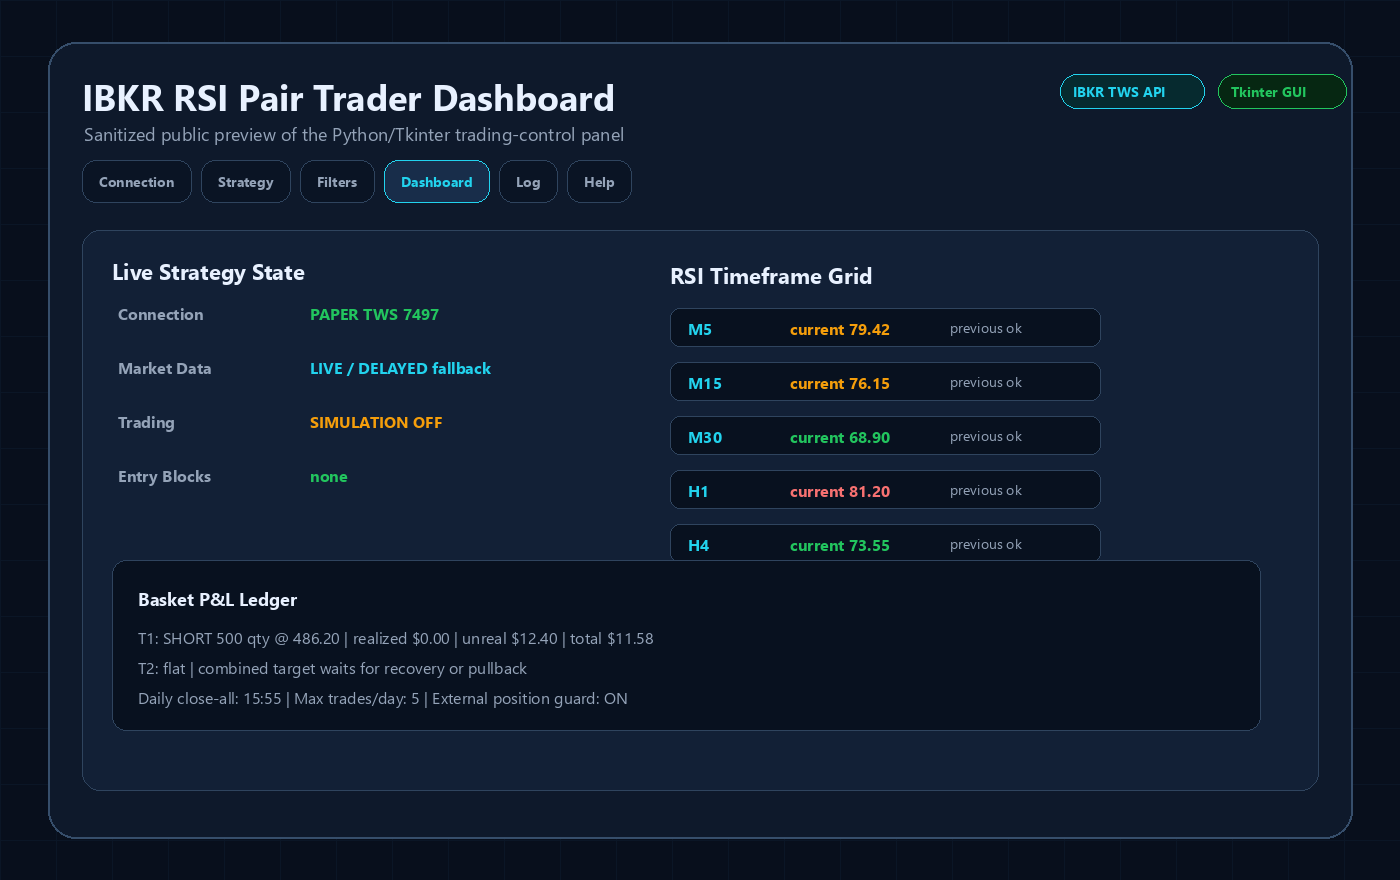
The strategy tracks Trade 1 and Trade 2 separately even though Interactive Brokers may net the actual broker position. Internal order references and fill accounting allow the app to calculate each basket leg.
Recovery trigger
Instead of hard-coding MT5 lot math, the Python version scales the recovery loss threshold from configured quantity blocks. This lets the same concept work for shares, forex quantity or other IBKR instruments.
Exit behavior
Trade 1 can close at its own target, while Trade 2 and the combined basket can close when the configured combined P&L objective is reached. Daily close rules can flatten positions near the chosen market close time.
Validation approach
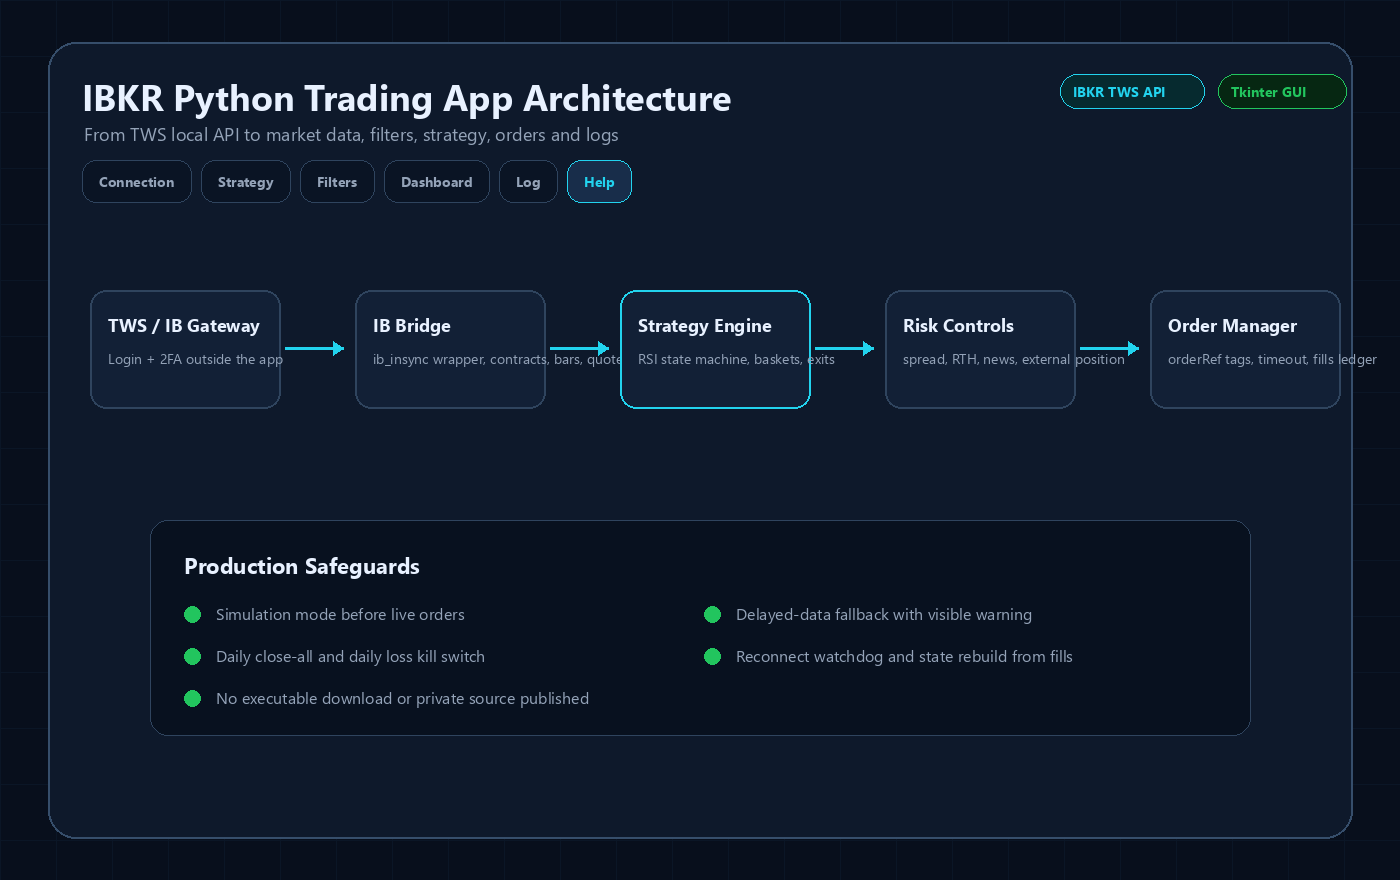
The safe path is paper testing first, then very small live quantity, with logs reviewed for RSI trigger, contract resolution, fill price, commission and session behavior.
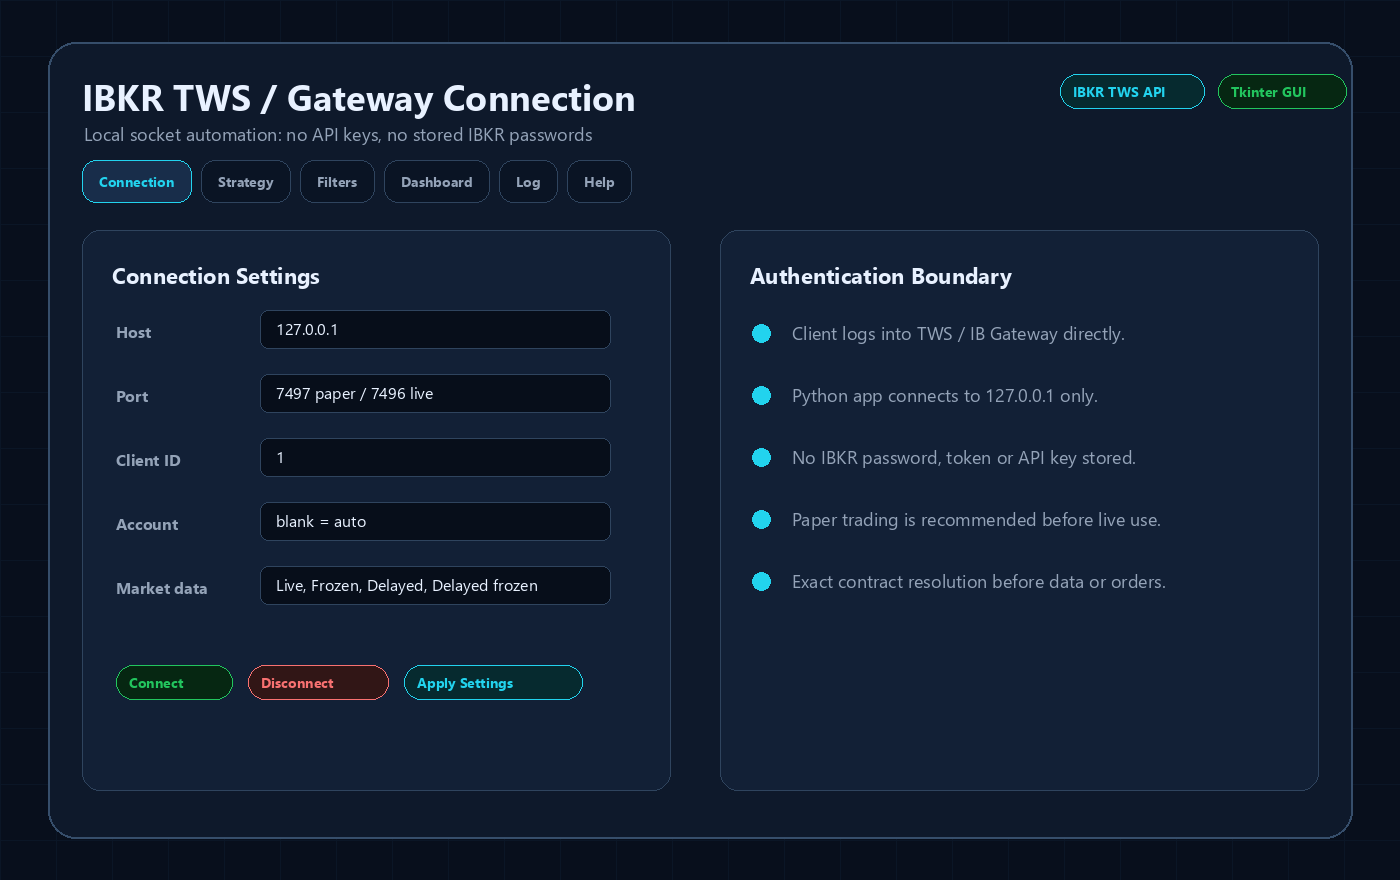
Sanitized Application Previews
These images are public UI previews based on the Tkinter application structure. They intentionally avoid real account IDs, live balances, broker credentials, downloadable executables and proprietary source code.
Important Risk and Security Notes
- This is software-development content, not investment advice or a profit guarantee.
- No IBKR username, password, 2FA code, account number, token, private executable or full source code is published here.
- Any live IBKR automation should be tested first in paper mode and reviewed against the current Interactive Brokers API behavior, account permissions and market-data subscriptions.
Related IBKR Python Guides
FAQ
Is RSI alone enough for a profitable strategy?
Not by itself. RSI is a signal component. Execution cost, spread, market regime, session timing, risk limits and validation matter heavily.
Can the RSI periods and thresholds be changed?
Yes. A client-ready app should expose period and threshold inputs instead of hard-coding them.
Can this be converted from an MT5 EA?
A logic port is possible, but broker execution and position accounting must be redesigned for IBKR because it is not the same runtime as MetaTrader.